Looking For a Great Mortgage? I’d Love To Work With You!
APPLY NOW

Let’s Connect! 604-506-1991

APPLY NOW

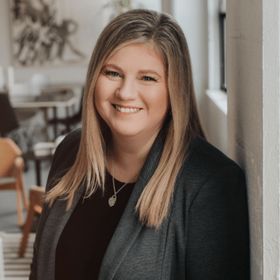
Tara Gentles, Mortgage Broker

Hello, I’m Tara Gentles, and I've been guiding clients through the complexities of mortgage financing since 2006, though my journey in lending began even earlier. Starting in the local credit unions, I quickly realized the need for a diverse range of products tailored to individual needs, which led me to become a broker.


As a Mortgage Expert with Brokers Squared, I leverage a vast network of lenders and products to ensure my clients secure the ideal mortgage at the most favorable rate.


Proudly calling Langley home, I prioritize flexibility, meeting clients at times and places convenient for them. Over the years, I've successfully facilitated financing for diverse clientele, from first-time homebuyers to seasoned real estate investors. With experience across all mortgage types, I consistently find optimal solutions for my clients, making the mortgage process straightforward with clear explanations of available options.


On a personal note, I cherish my role as a mom to three amazing grown humans. Embracing the philosophy that life is fleeting, I advocate for seizing the moment—whether it's embarking on spontaneous adventures or ensuring there's room in the budget for both practical savings and enjoyable experiences.


If you're considering mortgage financing, I'm here to assist. Please feel free to reach out at your convenience—I'd be honored to collaborate with you!

Nice things people have said about working with me.
Home Purchase
If you are looking to purchase a property, understanding all the mortgage options available to you can seem overwhelming. That’s where I come in, I do this everyday, and I love it. I will help you make sense of all the numbers guide you through the process.
Refinance
Are you looking to access some of the equity built up in your property? Maybe you want to consolidate some debts, start a new business, buy a vacation or investment property, or travel the world… regardless, let’s discuss all your mortgage options!
Renewal
If you are within six months of your mortgage renewal, or if your existing lender has sent you a renewal offer in the mail, I can give you a second opinion, and in most cases save you money. Never just sign the offer, there is always room to negotiate.
Contact Me Anytime
Obviously there are a lot more services I can offer and a lot more information I can share with you. Consider this my invitation to contact me with your questions. My goal is to set you up with the right mortgage for you, then help you build a plan to get rid of it.
Lenders

I have developed excellent relationships with lenders across the country, 
let’s figure out which one has the best products for you.
By Tara Gentles • October 6, 2026
Co-Signing a Mortgage in Canada: Pros, Cons & What to Expect Thinking about co-signing a mortgage? On the surface, it might seem like a simple way to help someone you care about achieve homeownership. But before you sign on the dotted line, it’s important to understand exactly what co-signing means—for them and for you. You’re Fully Responsible When you co-sign, your name is on the mortgage—and that makes you just as responsible as the primary borrower. If payments are missed, the lender won’t only go after them; they’ll come after you too. Missed payments or default can damage your credit score and put your financial health at risk. That’s why trust is key. If you’re going to co-sign, make sure you have a clear picture of the borrower’s ability to manage payments—and consider monitoring the account to protect yourself. You’re Committed Until They Can Stand Alone Co-signing isn’t temporary by default. Even once the initial mortgage term ends, you won’t automatically be removed. The borrower has to re-qualify on their own, and only then can your name be taken off. If they don’t qualify, you stay on the mortgage for another term. Before agreeing, talk openly about expectations: How long might you be on the mortgage? What’s the plan for eventually removing you? Having these conversations upfront prevents surprises later. It Affects Your Own Borrowing Power When lenders calculate your debt service ratios, the co-signed mortgage counts as your debt—even if you never make a payment on it. This could reduce how much you’re able to borrow in the future, whether it’s for your own home, an investment property, or even refinancing. If you see another mortgage in your future, you’ll want to consider how co-signing could limit your options. The Upside: Helping Someone Get Ahead On the positive side, co-signing can be life-changing for the borrower. You could be helping a family member or friend buy their first home, start building equity, or take an important step forward financially. If handled with clear expectations and trust, it can be a meaningful way to support someone you care about. The Bottom Line Co-signing a mortgage comes with both risks and rewards. It’s not a decision to take lightly, but with careful planning, transparency, and professional advice, it can be done responsibly. If you’re considering co-signing—or want to explore safer alternatives—let’s connect. I’d be happy to walk you through what to expect and help you decide if it’s the right move for you.
By Tara Gentles • September 22, 2026
Why a Mortgage Pre-Approval Protects Both Your Head and Your Heart There’s no denying it—buying a home is an emotional journey. In a competitive market, it can feel like you need to stretch beyond your comfort zone or bid above asking just to have a chance. That pressure can make it hard to separate what you want from what you can realistically afford. One of the biggest pitfalls buyers face is falling in love with a home that’s outside their price range. Once that happens, every other property seems like a compromise—even the ones that might have been a perfect fit otherwise. The best way to avoid this heartache? Get pre-approved before you start shopping. What a Pre-Approval Does for You A mortgage pre-approval gives you more than just a number—it provides clarity, confidence, and protection: Know your buying power : Shop within your true price range and avoid disappointment. Spot potential roadblocks : Uncover issues like credit bureau errors before you make an offer. Get organized : Learn exactly what documentation you’ll need so there are no surprises. Lock in a rate : Many lenders hold your rate for 30–120 days, giving you peace of mind if rates rise. Save yourself heartache : Protect yourself from falling for a home you can’t afford. Head vs. Heart Buying a home is about balance. Your head tells you what’s financially sound, your heart tells you what feels right—and both matter. A pre-approval helps bring those two sides together, so you can make confident choices without emotional stress clouding your judgment. The Bottom Line Looking at properties for fun is one thing—but if you’re serious about buying, a pre-approval is the smartest first step you can take. It sets realistic expectations, saves time, and protects your emotions along the way. If you’d like to explore your options and get pre-approved, I’d be happy to walk through the process with you. Let’s make sure you’re ready to shop with confidence.
By Tara Gentles • September 15, 2026
So, you’re thinking about buying a home. You’ve got Pinterest boards full of kitchen inspo, you’re casually scrolling listings at midnight, and your friends are talking about interest rates like they’re the weather. But before you dive headfirst into house hunting— wait . Let’s talk about what “ready” really means when it comes to one of the biggest purchases of your life. Because being ready to own a home is about way more than just having a down payment (although that’s part of it). Here are the real signs you're ready—or not quite yet—to take the plunge into homeownership: 1. You're Financially Stable (and Not Just on Payday) Homeownership isn’t a one-time cost. Sure, there’s the down payment, but don’t forget about: Closing costs Property taxes Maintenance & repairs Insurance Monthly mortgage payments If your budget is stretched thin every month or you don’t have an emergency fund, pressing pause might be smart. Owning a home can be more expensive than renting in the short term—and those unexpected costs will show up. 2. You’ve Got a Steady Income and Job Security Lenders like to see consistency. That doesn’t mean you need to be at the same job forever—but a reliable, documented income (ideally for at least 2 years) goes a long way in qualifying for a mortgage. Thinking of switching jobs or going self-employed? That might affect your eligibility, so timing is everything. 3. You Know Your Credit Score—and You’ve Worked On It Your credit score tells lenders how risky (or trustworthy) you are. A higher score opens more doors (literally), while a lower score may mean higher rates—or a declined application. Pro tip: Pull your credit report before applying. Fix errors, pay down balances, and avoid taking on new debt if you’re planning to buy soon. 4. You’re Ready to Stay Put (At Least for a Bit) Buying a home isn’t just a financial decision—it’s a lifestyle one. If you’re still figuring out your long-term plans, buying might not make sense just yet. Generally, staying in your home for at least 3–5 years helps balance the upfront costs and gives your investment time to grow. If you’re more of a “see where life takes me” person right now, that’s totally fine—renting can offer the flexibility you need. 5. You’re Not Just Buying Because Everyone Else Is This one’s big. You’re not behind. You’re not failing. And buying a home just because it seems like the “adult” thing to do is a fast way to end up with buyer’s remorse. Are you buying because it fits your goals? Because you’re ready to settle, invest in your future, and take care of a space that’s all yours? If the answer is yes—you’re in the right headspace. So… Are You Ready? If you’re nodding along to most of these, amazing! You might be more ready than you think. If you’re realizing there are a few things to get in order, that’s okay too. It’s way better to prepare well than to rush into something you're not ready for. Wherever you’re at, I’d love to help you take the next step—whether that’s getting pre-approved, making a plan, or just asking questions without pressure. Let’s make sure your homebuying journey starts strong. Connect anytime—I’m here when you’re ready.
By Tara Gentles • September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
By Tara Gentles • September 1, 2026
Thinking About Buying a Second Property? Here’s What to Know Buying a second property is an exciting milestone—but it’s also a big financial decision that deserves thoughtful planning. Whether you're dreaming of a vacation retreat, building a rental portfolio, or looking to support a family member with a place to live, there are plenty of reasons to consider a second home. But before you jump in, it's important to understand the strategy and steps involved. Start with “Why” The best place to begin? Clarify your motivation. Ask yourself: Why do I want to buy a second property? What role will it play in my life or finances? How does this fit into my long-term goals? Whether your focus is lifestyle, income, or legacy planning, knowing your “why” will help you make smarter decisions from the start. Talk to a Mortgage Expert Early Once you’ve nailed down your goals, the next step is to sit down with an independent mortgage professional. Why? Because buying a second property isn't quite the same as buying your first. Even if you’ve qualified before, financing a second home has unique considerations—especially when it comes to down payments, debt ratios, and how lenders assess risk. How Much Do You Need for a Down Payment? Here’s where the purpose of the property really matters: Owner-occupied or family use: You may qualify with as little as 5–10% down, depending on the property and lender. Income property: Expect to put down 20–35%, especially for short-term rentals or if it won’t be occupied by you or a family member. Your down payment amount can be one of the biggest hurdles—but with strategic planning, it’s often manageable. Ways to Fund the Down Payment If you don’t have the full amount in cash, you might be able to tap into your current home’s equity to help fund the purchase. Here are a few ways to do that: ✅ Refinance your existing mortgage to access additional funds ✅ Secure a second mortgage behind your current one ✅ Open a HELOC (Home Equity Line of Credit) ✅ Use a reverse mortgage (in certain age-qualified scenarios) ✅ Take out a new mortgage if your current home is mortgage-free These options depend on your income, credit, home value, and overall financial picture—another reason why having a pro in your corner matters. Second Property Strategy: It’s More Than Just Numbers This purchase should be part of a bigger financial plan—one that balances risk and reward. It’s about: Assessing your full financial health Maximizing your existing assets Minimizing your cost of borrowing Aligning your purchase with your long-term goals Ready to Take the Next Step? There’s no one-size-fits-all answer when it comes to buying a second property. That’s why it helps to talk things through with someone who understands both the big picture and the small details. If you’re ready to explore your options and build a plan to make that second property dream a reality, let’s connect. I’d love to help you take the next step with confidence.
By Tara Gentles • August 18, 2026
Don’t Forget About Closing Costs When planning to buy a home, most people focus on saving for the down payment. But the truth is, that’s only part of the equation. To actually finalize the purchase, you’ll also need to budget for closing costs —the out-of-pocket expenses that come up before you get the keys. Closing costs can add up quickly, which is why they should be part of your pre-approval conversation right from the start. Lenders will even require proof that you’ve got enough funds set aside. For example, if you’re getting an insured (high-ratio) mortgage, you’ll need at least 1.5% of the purchase price available in addition to your down payment. That means a 10% down payment actually requires 11.5% of the purchase price in cash to make everything work. Let’s break down some of the most common expenses you should prepare for: 1. Home Inspection & Appraisal Inspection : Paid by you, this gives peace of mind that the property is in good shape and doesn’t have hidden problems. Appraisal : Required by the lender to confirm value. Sometimes this is covered by mortgage insurance, sometimes by you. 2. Legal Fees A lawyer or notary is required to handle the title transfer and make sure the mortgage is properly registered. Legal fees are often one of the larger closing costs—unless you’re also responsible for property transfer tax. 3. Taxes Many provinces charge a property or land transfer tax based on the home’s purchase price. These fees can range from hundreds to thousands of dollars, so you’ll want to factor them in early. 4. Insurance Property insurance is mandatory—lenders won’t release funds without proof that the home is insured on closing day. Optional coverage like mortgage life, disability, or critical illness insurance may also be worth considering depending on your financial plan. 5. Moving Costs Whether you’re renting a truck, hiring movers, or bribing friends with pizza and gas money, moving comes with expenses. Cross-country moves especially can be surprisingly pricey. 6. Utilities & Deposits Setting up new services (electricity, water, internet) can involve connection fees or deposits, particularly if you don’t already have a payment history with the utility provider. Plan Ahead, Stress Less This list covers the big-ticket items, but every purchase is unique. That’s why it pays to have an accurate estimate of your personal closing costs before you make an offer. If you’d like help planning ahead—or want a breakdown tailored to your situation—let’s connect. I’d be happy to walk you through the numbers and make sure you’re fully prepared.